


DailyPay On-Demand Pay
4.718.87K Reviews
App Specs
- Version
- 52.0.0
- Updated On
- License
- Free
- Downloads
- 1,000,000+
- Developer
- DailyPay Inc
- Categories
- Finance
- Platform
- Android, iOS
Screenshots
 Analysis by AppCompare
I find the idea behind DailyPay easiest to understand as a change in timing: instead of treating payday as the only moment when your earnings become useful, the app can let you draw on wages you have already earned before the usual pay date. That can matter when a necessary expense arrives at an inconvenient point in the pay cycle. It is not extra income, though; it shifts some money forward, so the value depends on whether you need that flexibility and can plan around the smaller amount left for payday.
What early access changes in everyday budgeting
Most budgeting routines start with a pay date and divide that incoming amount among bills, groceries, transport, and savings. DailyPay changes that rhythm by making some earned wages available earlier. In my view, the most useful effect is not simply being able to transfer money sooner. It is having another way to handle a timing mismatch, such as a bill due before the next paycheck even though the work that earned the money has already been done.
That distinction helps set realistic expectations. The app is a finance tool, not a raise, a loan that creates new earnings, or a replacement for a regular budget. If I use an early transfer to cover an expense, I need to remember that those wages will not also be available in full on payday. Thinking of it as moving part of a paycheck forward makes the choice clearer and helps prevent the app from feeling like a fresh pool of spending money.
How I would approach setup and the first transfer
The experience begins with setting up an account and connecting it with an employer that works with the service. That employer connection is central: this is not a general wallet where anyone can add earnings from any job. Before relying on it for an urgent bill, I would first confirm that my employer is supported and take time to understand what the app shows as available. That small bit of preparation is more useful than installing it only when a payment deadline is already close.
After setup, the basic workflow is straightforward: check the displayed amount, decide whether a transfer is genuinely needed, and review the relevant details before confirming. I would treat the available balance as a planning aid rather than a target to withdraw. A practical habit is to check it when reviewing upcoming bills, then transfer only enough to solve the immediate problem. That keeps the app focused on cash-flow support instead of encouraging casual withdrawals simply because they are possible.
DailyPay is made by DailyPay Inc and is a free finance app for everyone. Its average rating is 4.7 from around 226,000 ratings, with about 18,000 written reviews and over 1 million installs. The current version is 48.0.0, and it requires Android 9 or later. Those figures suggest that many people have tried it, but I would still judge whether it fits my own employer and budgeting habits rather than treating popularity as a guarantee that it will suit every worker.
How Does DailyPay Work?
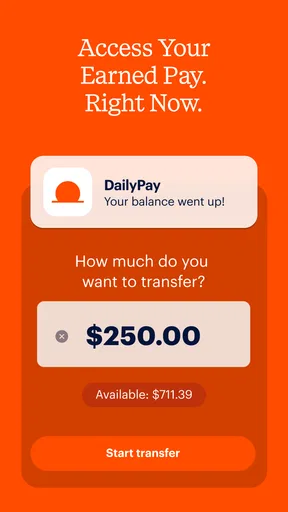
Alright, let's dive into how this magical app functions. Basically, DailyPay partners with your employer to give you access to your earnings as you earn them. No more waiting until the end of the month or the fortnight. You can see exactly how much money you've earned and transfer the amount you need straight to your bank account. It's like payday every day, or at least whenever you need it!
Worth Reading Before You Choose

EA SPORTS FC Mobile 26 Is a Bigger Football Game, but It Takes Time

Flipboard Shows What News Apps Must Do Beyond the Feed

Switching to Android Auto Means Rethinking Your Driving Routine

Google Calendar Makes a Crowded Week Easier to Manage

Ludo King Makes the Most of the Minutes Between Plans

Baby Panda World Brings Quick Play to Modern Phones, but Its Game Library Feels Busy
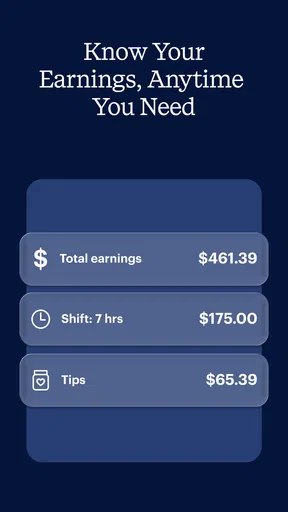
Once you've downloaded the app, you'll need to set up an account and link it to your employer. The app's interface is super user-friendly, with a clean design that makes it easy to navigate. You can check your available balance, view your earnings history, and make transfers all in a few taps.
What I Love About DailyPay
One of the things that really stands out about this app is the flexibility it offers. Need to cover an unexpected bill or treat yourself to something nice? No problem. DailyPay gives you the freedom to access your money when you need it, rather than being tied to a rigid payday schedule.
The app also offers a nice level of transparency. With real-time earnings updates, you always know exactly where you stand financially. This feature is a game-changer for budgeting and helps avoid any nasty surprises.
And let’s not forget the notifications! DailyPay keeps you in the loop with reminders and updates, ensuring you're always aware of your financial status. It’s like having a personal financial assistant!
A realistic use for the flexibility
Imagine that a routine household bill is due a few days before payday, and an unexpected car or travel expense has already tightened the week’s budget. If the app shows earned wages available, an early transfer could help cover the bill without turning to a credit card or asking someone else to bridge the gap. I would use it for that specific shortfall, then adjust the rest of the week’s spending because the next paycheck will be lower by the amount brought forward.
This kind of scenario is where the service makes the most sense to me: the expense is necessary, the timing is awkward, and the person using the app has a plan for the next pay period. It is less compelling for an optional purchase that can wait. If I withdraw early for a treat and then face a required bill later, the convenience can simply move the stress rather than remove it.
Trade-offs to think through before relying on it
While DailyPay is awesome, there are a few things to keep in mind. First, there may be a fee for transferring funds, depending on your employer's setup. It's crucial to be aware of any potential costs to avoid eating into your hard-earned cash.
Also, while accessing your wages early can be incredibly helpful, it's important to use this feature wisely. It might be tempting to dip into your earnings frequently, but remember that this could leave you short on a future payday. It’s all about striking a balance and using this tool to support your financial health, not hinder it.
For me, the best safeguard is to compare the transfer option and its cost with the alternatives before acting. If a bill can be paid on its due date without a penalty, waiting may be cheaper and simpler. If delaying it would cause a larger problem, an early wage transfer may be worth considering. The app’s usefulness therefore depends not only on access but also on the particular terms available through an employer and the urgency of the expense.
There is also a habit risk that is easy to overlook. When money becomes visible before the regular payday, it can feel more available than it really is. I would avoid checking the balance as a cue to spend and instead check it when making a concrete plan. Looking at the next pay period before transferring can help: list the bills that will still need covering, decide what amount must remain untouched, and only then consider whether an early draw solves a genuine timing issue.
How it compares with waiting, saving, or borrowing
Compared with simply waiting for payday, DailyPay offers more flexibility when the calendar and a bill’s due date do not line up. Compared with building a small emergency buffer, however, it does not create a reserve; it provides earlier access to earnings that are already yours. A savings cushion can be more dependable for recurring surprises because it does not reduce the next paycheck, while early wage access may be useful when that cushion has not yet been built or is temporarily depleted.
It is also different from credit. A credit card or loan can involve borrowing and repayment obligations, while this app centers on earned wages. That does not automatically make every transfer the best choice: any applicable transfer charge and the effect on payday still matter. If I can wait without a late fee or other consequence, waiting is often the cleaner option. If I need to borrow repeatedly just to cover ordinary expenses, I would see that as a sign to revisit the budget rather than rely on early access as a permanent fix.
Another alternative is asking a bill provider whether a due date can be changed or a payment arrangement is available. That may solve a recurring timing problem without taking money from a future paycheck. DailyPay is more directly useful when the need is immediate and the employer connection is in place; a due-date adjustment or savings habit may work better for a predictable monthly squeeze.
Who is most likely to benefit
I think DailyPay is best suited to someone whose employer supports it, who sometimes faces a gap between earned income and a necessary expense, and who can keep track of what has been moved forward. It may be especially helpful for workers whose bills do not neatly fall after payday, provided they use the app selectively and understand the transfer terms that apply to them.
It is not the right fit for everyone. If an employer is not connected to the service, the central function is not available. If someone already spends their full paycheck as soon as it arrives, taking part of it early could make the following pay date harder. And if the main problem is that total income does not cover regular costs, changing the timing alone cannot close that gap. In those situations, a longer-term budget review, a payment-date change, or appropriate financial guidance may be more useful than frequent transfers.
Questions worth resolving before an urgent moment
Before depending on the app, I would check whether my employer participates, what amount is actually available, and what the transfer will cost under my employer’s setup. I would also make sure I understand how an early transfer affects the amount I expect on payday. Those are practical questions to settle calmly, not while standing at a checkout or trying to meet a deadline.
I would also consider whether the timing of a transfer suits the bill. A displayed balance does not by itself mean that every transfer method or arrival time will match an immediate payment need, so I would verify the choices shown in the app before counting on the money. The same goes for notifications: they can help keep earnings in view, but I would use them as reminders to plan, not as prompts to withdraw.
The app’s store release date is December 7, 2018, and its content rating is Everyone. For me, those details are less important than whether the service fits my workplace and whether I can use early access without undermining the next pay period. The free download is only the starting point; transfer terms and personal habits determine the real value.
Things to Consider
While DailyPay is awesome, there are a few things to keep in mind. First, there may be a fee for transferring funds, depending on your employer's setup. It's crucial to be aware of any potential costs to avoid eating into your hard-earned cash.
Also, while accessing your wages early can be incredibly helpful, it's important to use this feature wisely. It might be tempting to dip into your earnings frequently, but remember that this could leave you short on a future payday. It’s all about striking a balance and using this tool to support your financial health, not hinder it.
Final Thoughts
DailyPay is a fantastic tool for anyone who wants more control over their finances. It offers a practical solution to cash flow issues, allowing you to access your money when you need it most. The app’s design is intuitive, making it easy for anyone to use, whether you're tech-savvy or not.
Just remember, with great power comes great responsibility. Use DailyPay as a stepping stone to better manage your finances, and you’ll find it to be an invaluable companion on your financial journey. Ready to take control of your payday? Go ahead and give DailyPay a spin!
Pros
- Immediate access to earned wages.
- User-friendly interface for easy navigation.
- Supports various payment methods.
- Strong data security features.
- Reduces financial stress for users.
Cons
- Requires employer participation.
- May incur transaction fees.
- Limited to certain regions.
- Dependent on app stability.
- Does not replace financial planning.
FAQs for DailyPay On-Demand Pay
What is DailyPay On-Demand Pay and how does it work?
DailyPay On-Demand Pay is a financial app that allows employees to access their earned wages before payday. Once your employer is integrated with DailyPay, you can request a portion of your earned wages through the app. The funds are then transferred to your bank account or debit card, providing flexibility in managing your finances.
Is DailyPay On-Demand Pay secure and safe to use?
Yes, DailyPay On-Demand Pay prioritizes user security by employing encryption and security protocols to protect personal and financial information. The app adheres to industry standards and regulations, ensuring that your data is safe. Users can also enable additional security features such as two-factor authentication for enhanced protection.
Are there any fees associated with using DailyPay?
DailyPay offers different transfer options, some of which may incur fees. Instant transfers typically have a minor fee, while standard transfers are often free and may take one to three business days. It's important to review the fee structure within the app to understand any costs associated with accessing your wages early.
Who can use DailyPay On-Demand Pay?
DailyPay is available to employees of partnered companies that have integrated the service into their payroll systems. If your employer offers DailyPay, you can sign up and use the app. Check with your HR department to see if this service is available at your workplace and how you can enroll.
How does using DailyPay affect my regular paycheck?
Using DailyPay does not affect the total amount of your regular paycheck. It simply allows early access to your earned wages. On payday, your paycheck reflects the remaining balance after deducting any amounts already accessed through DailyPay. This service provides flexibility without altering your overall earnings.


